When Fee Streams Trade Below Par: London’s Asset Managers and the 2026 Bid for Control
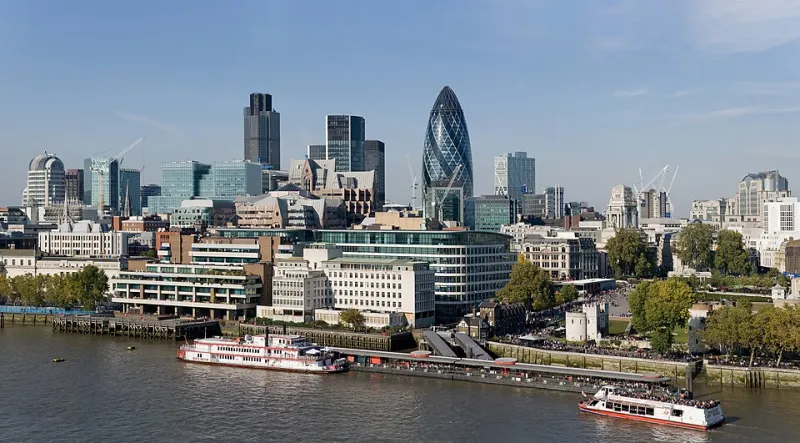
Photo: David Illif with image-alignment and Photoshoping by User:Colin and Kim Hansen, CC BY-SA 4.0, via Wikimedia Commons
The London market has spent much of the past decade applying a haircut to asset-management equity. The discount has been persistent enough to become a feature of the sector rather than a temporary aberration. In 2026, with overseas private-capital buyers and US strategics showing renewed interest in UK-listed managers, the question is no longer whether the discount exists. It is what the discount is trying to tell us.
The Discount Is a Verdict, Not an Anomaly
A listed asset manager is, in theory, a clean way to own a fee stream. It requires little tangible capital, generates cash, and benefits from scale. In practice, the equity market treats that fee stream as a call option on markets, flows and fee rates — all of which can move against the owner at once. When markets fall, assets under management fall, revenue falls and clients redeem. When markets rise, passive and platform competition caps the upside. The result is a sector that trades at a persistent discount to the value of its assets under management, and often to the sum of its parts.
That discount is not simply a failure of London liquidity. It reflects a judgement about durability. Public shareholders bear redemption risk, key-person risk, regulatory risk and the cost of distribution. They also bear the cyclicality of performance fees and the opacity of institutional mandates. A private buyer can look through some of that volatility. A public market cannot.
What a Private Buyer Sees in a Public Fee Stream
Private-capital buyers are not paying for the same thing as public shareholders. They are buying control of a distribution machine and a set of fee streams that can be re-engineered. A take-private can replace public-market reporting with private capital, seed new strategies, push products through wealth platforms, and cross-sell into private vehicles. The buyer may accept a lower headline return because it can use structure — permanent capital, co-investment, leverage at the holding company — to enhance the equity return.
That is the arbitrage. It is not merely that London is cheap. It is that the private owner can hold the asset through a cycle, while the public market marks it every day. The bid premium is the price of escaping that marking regime. For shareholders, that can be a welcome exit. For fund investors, it changes the ownership map.
The Saver’s Ledger: Choice, Distribution and Fee Pressure
UK savers do not usually buy asset managers directly. They meet them through DC pensions, platforms, ISAs and advised portfolios. Consolidation among listed managers therefore matters less at the level of the ticker and more at the level of the shelf. Fewer independent managers can mean less choice, greater bargaining power for distributors, and a stronger incentive to compete on distribution rather than on investment outcomes.
That is not automatically bad. Scale can lower costs, improve technology and fund research. But the risk is a market where fee pressure is transmitted through distribution agreements rather than through transparent competition. A private owner with a concentrated product range may prioritise asset gathering in higher-margin areas. Consumer Duty has raised the bar on value for money, yet the governance of private ownership is less visible to the end investor than a listed board and an annual general meeting.
The Governance Test After the Bid
The public market is an imperfect disciplinarian, but it does impose disclosure. A listed manager publishes flows, margins and staff costs. It answers to independent directors. A private owner answers to its own investors and lenders. That can be a more patient structure, but it can also be a more opaque one. Fund boards, the FCA and independent governance committees become the main check on conflicts between the owner and the fund investor.
The critical questions are familiar. Who seeds new strategies, and on what terms? How are related-party services priced? Does the owner have an incentive to push fund investors into higher-margin private vehicles? None of these is unique to private ownership. But take-private deals concentrate them. The bid premium is paid to shareholders; the governance burden shifts to the people whose money is managed.
A Market-Structure Question
London’s listed asset-management sector is small, but it is part of the market’s plumbing. It provides public equity exposure to a fee-based industry and gives UK investors a way to own the managers they use. If the mid-tier continues to leave the market, the remaining listed names will be larger and more global. That may be efficient. It may also leave the UK public market with less diversity and fewer domestic champions.
The deeper issue is whether London can price long-duration fee streams at all. If the answer is no, private ownership becomes the default. That is a market-structure question, not a sentiment story. The discount will narrow only when managers can demonstrate durable net flows, cost discipline and a credible answer to passive and platform competition. Until then, 2026 is likely to bring more bids. The bid is the symptom. The discount is the diagnosis.