Private Credit’s Mid-Market Claim: Yield, Covenants and London’s 2026 Refinancing Cycle
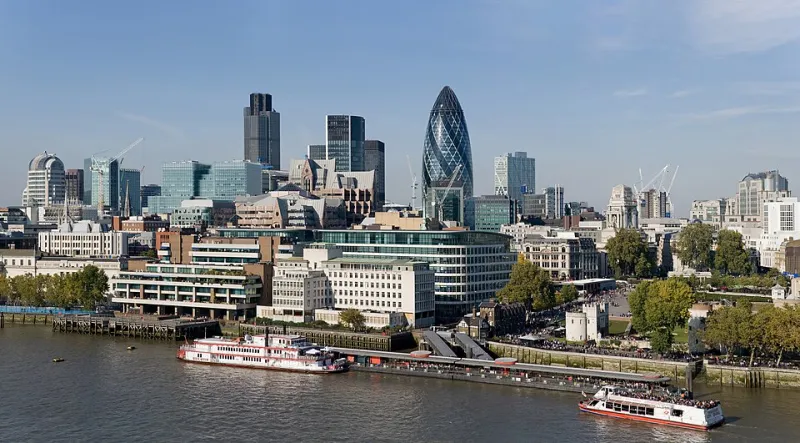
Photo: David Illif with image-alignment and Photoshoping by User:Colin and Kim Hansen, CC BY-SA 4.0, via Wikimedia Commons
The UK mid-market refinancing calendar is not a headline about gilt yields. It is a capital-stack story. Companies that borrowed when money was cheap are now approaching maturity walls with higher coupons, more selective banks and a public syndicated loan market that has become less accessible for smaller issuers. Private credit funds have stepped into that space. For UK pension schemes and wealth managers, the appeal is obvious: floating-rate income, bespoke documentation and a yield premium over public credit. The risk is equally obvious, though less often priced: illiquidity, covenant complexity and valuations that are not set by a transparent secondary market.
The refinancing calendar in plain terms
Many UK mid-market companies refinanced during the low-rate period. As those facilities mature, borrowers face a different funding environment. Banks remain willing to lend to strong credits, but they are more selective on size, sector and leverage. The syndicated loan market can be efficient for larger issuers, but smaller companies often lack the scale to justify a public deal. Private credit offers speed, confidentiality and the ability to tailor a facility to a company’s cash flow. That is a genuine service, not a marketing story.
The cost of that service is borne by the borrower and, indirectly, by the investor. Private credit loans typically carry higher margins than bank facilities or public bonds. The investor receives a yield premium, but that premium is compensation for credit risk, illiquidity, origination risk and the absence of daily price discovery. The relevant question is whether the premium is adequate, not whether it exists.
Who lends in London’s private credit market
The London ecosystem is diverse. It includes specialist direct lending managers, diversified private credit platforms, US managers with London offices, UK pension schemes investing through mandates, insurers and wealth platforms. Some funds focus on senior secured lending. Others move up the capital stack into unitranche, mezzanine or preferred equity. The risk profile changes at each layer.
For investors, the label ‘private credit’ is too broad to be useful on its own. A senior secured loan to a profitable UK services company is not the same as a mezzanine position in a leveraged buyout. The former may offer lower yield and stronger covenant protection; the latter may offer higher yield and greater recovery uncertainty. The investor should know which layer of the capital stack is being purchased and who stands ahead in the queue.
Yield versus illiquidity
Private credit yields can look attractive relative to public credit, but the comparison is not straightforward. Public bonds are marked daily and can be sold, subject to market conditions. Private loans are typically valued using model-based marks, borrower performance data and manager judgement. That does not make the valuations wrong, but it does make them less observable. In a stress scenario, the gap between the mark and the achievable sale price can widen quickly.
Redemption terms matter. Some vehicles offer periodic liquidity; others are closed-ended or have gates. Wealth managers should not assume that a private credit fund can be sold at short notice without a discount. Pension schemes should consider the liquidity profile of their overall portfolio, not just the yield on the private credit allocation. An income stream that cannot be accessed when needed is not a substitute for cash or short-dated government bonds.
Covenants and recovery
Covenant analysis is where private credit due diligence earns its keep. Investors should ask whether the loan has maintenance covenants or covenant-lite incurrence tests, how EBITDA is defined and adjusted, whether payment-in-kind interest is permitted, and what security is available. They should also ask how the manager has behaved in previous workouts. Recovery rates are not a theoretical exercise; they depend on documentation, creditor position and the willingness of the manager to enforce.
Mid-market borrowers often have concentrated customer bases, sponsor ownership or cyclical cash flows. Those features are not disqualifying, but they require underwriting discipline. A higher yield can be a fair price for those risks. It can also be a warning that the lender is being compensated for a risk it does not fully understand.
What pension schemes and wealth managers should require
Before treating private credit as a safe income substitute, UK investors should demand transparency on valuation policy, default and recovery experience, fee structures and liquidity terms. They should ask for stress testing under a higher-for-longer rate scenario and a weaker UK growth scenario. They should understand whether the manager has genuinely originated the loans or is buying participations in the secondary market.
Governance matters too. A private credit allocation should fit the scheme’s or client’s risk budget, not simply fill a yield gap. For DC schemes, daily dealing and member liquidity requirements may make some private credit structures unsuitable. For wealth managers, suitability depends on the client’s time horizon and tolerance for valuation uncertainty.
The 2026 test
Private credit can be a genuine source of income for UK investors, particularly where banks and public markets have retreated. But it is not public fixed income with a higher coupon. The 2026 refinancing cycle will test underwriting standards, covenant discipline and the honesty of valuations. Investors who treat private credit as a safe substitute for gilts or investment-grade credit may discover that the yield was compensation for risks they had not fully priced.