Quoted but Not Traded: Execution Risk in London's Smaller Companies
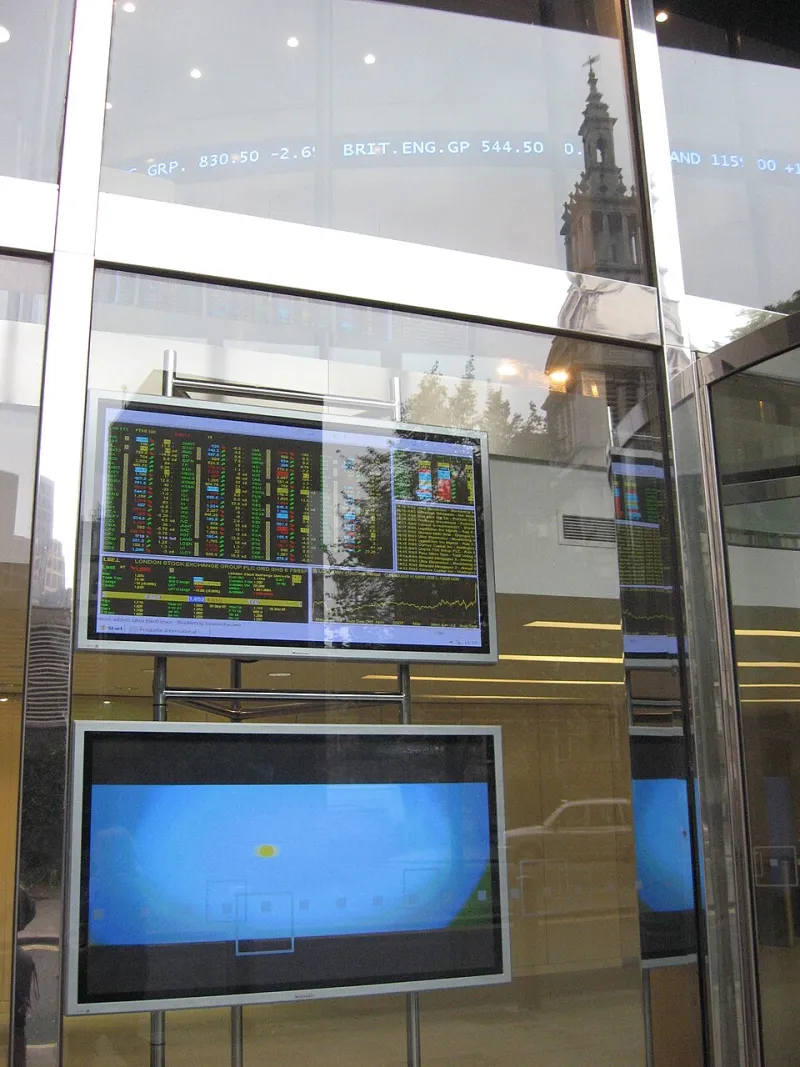
Photo: Kaihsu Tai, CC BY-SA 3.0, via Wikimedia Commons
A share price is a claim about value. A dealing spread is a claim about certainty. For a large and growing part of London's smaller quoted segment, the second claim has become the more informative of the two, and the gap between what a stock is worth and what it costs to own is where portfolios quietly lose money.
The problem is not that small-caps have become unfashionable. It is that a market can continue to quote without meaningfully trading, and an index constituent can continue to publish a price that no institution of any size would transact against. Illiquidity has stopped being a footnote in the risk section of a factsheet and has become the defining characteristic of the asset class.
A market that quotes rather than trades
The mechanics are unglamorous. On a typical day, the order book beneath the top of the queue in a £150m–£400m company is thin to the point of being decorative. A retail order of £5,000 clears without incident. An institution seeking to build or exit a 1 per cent position does not, and the difference between the two experiences is the whole story.
Market-making in London's mid and small-cap universe has concentrated. Fewer firms quote, and those that do size their risk more defensively than a decade ago. The withdrawal of research coverage that followed the unbundling of commission has thinned the analytical base from which liquidity decisions are made, and the fragmentation of retail order flow across platforms and dark venues has dispersed the natural counterparties that once absorbed size.
On the buy side, the retreat has been just as consequential. Defined benefit schemes have matured into buyout and de-risking; their appetite for sub-£1bn equities has shrunk with them. Consolidation among UK asset managers has removed decision-makers who specialised in the segment. Several sterling-denominated funds that once provided a reliable bid have closed or re-based towards larger companies and overseas listings. What remains is a narrower pool of specialist capital, and specialists know their scarcity value.
The arithmetic of the round trip
Most investors model the entry price and the exit price, but not the cost of getting from one to the other. A round trip in an illiquid name is a sequence of frictions: the quoted spread, the slippage as size crosses the book, the commission, and stamp duty at 0.5 per cent on the way in for most UK-incorporated shares. On a mid-cap with a 25 basis point spread and reasonable depth, the total is manageable. On a smaller company with a spread of 3 to 5 per cent and a book that thins after the first £40,000, the round trip can consume a meaningful share of a two-year return before any thesis has had time to prove itself.
There is a second, subtler cost. When a position cannot be exited quickly, the manager's holding period stops being a choice and becomes a constraint. The stock is no longer a view; it is a hostage. That is a governance problem as much as a dealing one, and it is why an apparently generous valuation discount on a thinly traded name should be read as compensation for a risk that a spreadsheet will not capture.
Five measures worth running before you deal
The following is not a substitute for fundamental research. It is a filter that sits in front of it.
1. Quoted spread as a percentage of mid. Take the average across the session, not a single glance, and compare it with peers of similar size. A spread that widens sharply at the close or around announcements is telling you who is present and who is not.
2. Depth at the touch. Ask a broker, or use the venue data, to see what size the displayed quotes actually represent. A two-way price for 500 shares is a courtesy, not a market.
3. Days to liquidate at 20 per cent of average daily volume. This is the standard institutional yardstick, and it should be computed for the position the fund intends to hold, not the position it can buy on day one. Ten days is uncomfortable; thirty is a structural exposure.
4. Free float and holder concentration. A company 70 per cent owned by founders, family vehicles and two institutions has a small effective float regardless of its market capitalisation. Concentration also creates a cliff-edge: when one holder decides to leave, everyone sees it.
5. Forced-seller overlap. Identify which mandates own the stock, and under what circumstances they must sell. A name widely held by open-ended funds facing redemptions carries an execution risk that has nothing to do with its business.
Discount, or trap?
The awkward question for UK investors is whether the persistent small-cap discount to larger peers is an opportunity or simply the correct price for a structural handicap. There are genuine bargains: companies with net cash, contracted revenue and a plausible route to index inclusion or trade sale, where the illiquidity premium exceeds the friction. Takeover activity in the segment has, in recent years, repeatedly validated valuations that public markets declined to recognise.
But a discount is only a bargain if the exit exists. When a bid arrives, it arrives for everyone; when it does not, the holder is left with the spread. That asymmetry explains why the segment's aggregate rating can remain depressed even as individual names look cheap.
What would change the picture
Three things, none of them quick. Consolidation of the UK pension system into larger pools, if it eventually produces mandates with explicit small-cap allocations, would restore a structural bid. A genuine simplification of how retail platforms route orders could improve the quality of the book. And a healthier pipeline of new issues would give the segment the secondary liquidity that only scale provides.
Until then, the discipline is arithmetic. Size positions to the exit, not the entry. Price the round trip before the thesis. And treat a quoted price on a quiet afternoon as an estimate, not an offer.